

Chatham Lodging Trust is a Real Estate Investment Trust (REIT) specializing in investing in upscale and premium-branded select-service hotels and extended-stay hotels. The company was initially founded in 2009 and is based in Palm Beach, Florida, in the US. It operates as a self-advised, fully-integrated REIT, earning income through investment in hotel properties, hotel performance, and leasing of its properties.
As a REIT, Chatham Lodging Trust has a unique business model. REITs purchase and manage income-producing real estate such as apartments, shopping centers, offices, and hotels. They allow individual investors to earn returns from real estate—without having to buy, manage, or finance any properties themselves. For Chatham, the focus is on upscale, extended-stay hotels and premium-branded, select-service hotels. It typically works with significant brands like Residence Inn, Homewood Suites, Hyatt Place, and Hampton Inn.
As of the end of 2021, Chatham Lodging Trust's portfolio included ownership interests in 86 hotels totaling approximately 11,760 rooms/suites. They own hotels in 15 states and the District of Columbia. Chatham Lodging's specialty in upscale select service and extended stay hotels sets the company apart from other hospitality REITs. These types of hotels typically have better operating margins than larger, full-service hotels.
In addition to owning hotel properties, the company also receives income by leasing its hotel properties to third-party operators, who run the day-to-day operations of the hotels under the umbrella of well-known hotel franchises. By doing so, the company is able to collect the lease income without the hassle of running a hotel.
As with any real estate company, Chatham Lodging Trust is susceptible to the peaks and troughs of the real estate market. Yet, the company has remained resilient despite these market fluctuations demonstrating consistent returns.
It’s important to mention that, in order to maintain its REIT status, Chatham Lodging Trust is required to distribute at least 90% of its taxable income to shareholders annually, via dividends. This is something that makes Chatham Lodging Trust, as with many REITs, appealing as an investment. As such, investors looking for a stake in the real estate sector, particularly in the hospitality and lodging niche, might consider Chatham Lodging Trust REIT (CLDT) as a potential portfolio addition.
Income statement
Balance sheet statement
Cash flow statement
Current assets / Current liabilities
Equity / Debt / Cash
Dividends

Chatham Lodging Trust has appointed Liam Brown to its board of trustees as an independent director, effective immediately. Brown, who recently retired from Marriott International as group president for the U.S. and Canada, brings extensive lodging expertise and experience in operations and franchisor/franchisee relationships to Chatham's board. His appointment is expected to provide substantial insights to enhance shareholder value through maximizing operating results and capital allocation decisions.
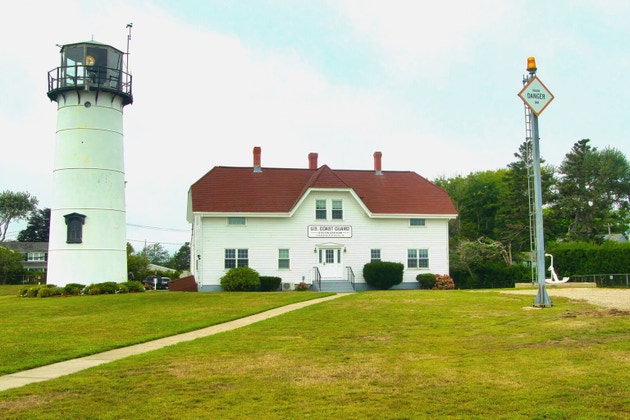
Chatham Lodging Trust (CLDT) has seen a significant increase in share price and total return since March, outperforming its hotel REIT peers. The company raised its AFFO guidance to $1.28–$1.34/share due to strong Q2 results, margin expansion, and record RevPAR, especially in Silicon Valley. While the valuation discount has narrowed, CLDT is still considered undervalued compared to its peers, maintaining a "Buy" rating based on its strong balance sheet and potential upside from the Silicon Valley recovery.

Chatham Lodging (CLDT) has received an upgrade to a Zacks Rank #2 (Buy), primarily due to an upward trend in its earnings estimates. This positive outlook suggests potential buying pressure and an increase in its stock price, as earnings estimate revisions are strongly correlated with near-term stock movements. The Zacks Rank system, which effectively uses these revisions, indicates that CLDT's improved earnings picture makes it a strong candidate for market-beating returns.
Chatham Lodging Trust (NYSE:CLDT) has received a consensus "Hold" rating from analysts, with an average 12-month price target of $13.00. The REIT recently surpassed quarterly earnings and revenue expectations, reporting $0.13 EPS against an $0.11 estimate and $87.8 million in revenue compared to an $82.01 million forecast. CLDT shares traded near the target price, and the company announced a quarterly dividend of $0.10 per share, yielding 3.1% annually.
Wall Street Zen has upgraded Chatham Lodging Trust (NYSE: CLDT) from a "hold" to a "buy" rating, despite the broader analyst consensus remaining "Hold" with an average price target of $13.00. The company recently reported strong quarterly earnings of $0.13 per share, exceeding the $0.11 consensus, and revenue of $87.8 million, surpassing expectations. Institutional investors hold a significant 88.37% of the stock, and the REIT owns 39 hotels across 16 states and Washington, D.C.
Zacks Research downgraded Chatham Lodging Trust (NYSE:CLDT) from a "strong-buy" to a "hold" rating, aligning with the broader analyst consensus of "hold" and an average price target of $13.00. Despite the downgrade, Chatham Lodging Trust exceeded its recent quarterly expectations, reporting $0.13 EPS against an $0.11 consensus and $87.8 million in revenue versus $82.01 million expected. Institutional investors hold a significant 88.37% of the company's shares.