

Warrior Met Coal, Inc., known by the ticker symbol HCC on the New York Stock Exchange, is a leading producer and exporter of metallurgical coal in the global market. The Alabama-based company is predominantly focused on supplying high-quality metallurgical coal to some of the largest steel manufacturers in the world.
Established in 2015, Warrior Met Coal was born from the bankruptcy of Jim Walter Resources, a subsidiary of Walter Energy, when it was acquired by a group of its biggest creditors. Their mines and properties in Alabama's Tuscaloosa County played a significant role in the revival of the company. Now, it is a significant employer in the region, contributing to the local economy and to the international metallurgical coal industry.
Warrior Met Coal does not merely extract coal but specializes in hard coking coal, an essential ingredient in the steelmaking process. Its operations result in a low-cost, low volatile matter, high carbon content coal with strong coking properties – making it an invaluable resource for steel manufacturers.
The company operates two underground mines in Alabama, Mine No. 4 and Mine No. 7, recognized as among the longest horizontal mines in North America. The strategic geographic location of its mines enables the company to serve customers in both the Atlantic and Pacific Basin markets, cementing its place as a significant player in the export met coal market.
In terms of sustainability, Warrior Met Coal is proactive about reducing its environmental impact. Aware of the potential negative consequences of coal extraction, the company strives to meet or exceed all environmental laws and regulations. As part of its environmental stewardship, it maintains an active reforestation program and prioritizes the protection of water resources.
HCC's commitment to safety is evident in its operations and safety practices, evidenced by its receipt of the Sentinels of Safety Award, the nation's highest safety award for mining operations, testifying to its commitment to the safety of its employees.
In a rapidly evolving economic landscape, Warrior Met Coal, Inc. has established itself as a key supplier in the global steel industry, making it a crucial player in the metallurgical coal market. Its commitments to safety, sustainability, and the production of high-quality met coal define the essence of the company, ensuring a promising future in a competitive market.
Income statement
Balance sheet statement
Cash flow statement
Current assets / Current liabilities
Equity / Debt / Cash
Dividends

Warrior Met Coal (HCC) has seen a recent 15% share price fall despite strong longer-term performance, trading at $88.95. The company is considered 18% undervalued by analysts, with a fair value estimate of $108.50, driven by the early and on-budget launch of its Blue Creek longwall mine expected to increase production and improve margins. Investors are urged to consider both the current discount and potential risks like weak global steel demand before making investment decisions.

Warrior Met Coal Inc (HCC) shares surged 4.1%, but the stock appears significantly overvalued at $92.10 against a GF Value of $69.12. Despite a strong GF Score of 84/100, indicating robust financial strength, profitability, and growth, the valuation and momentum ranks are low. Furthermore, significant insider selling of $26.4 million without any buying suggests caution for potential investors.
This article identifies three potentially undervalued stocks—Amazon.com (AMZN), Warrior Met Coal (HCC), and PJT Partners (PJT)—based on their discounted future cash flow values. It highlights each company's operations, estimated discount to fair value, and recent financial performance, while noting that future growth forecasts for some are slower than market averages despite current undervaluation. The piece also provides a broader list of undervalued US stocks based on cash flows.
RBC has increased its price target for Warrior Met Coal (HCC) to $110 from $90, while maintaining a "Sector Perform" rating on the stock. This adjustment reflects a more optimistic outlook from the analyst firm on the steelmaking coal producer. The article also provides recent news and financial data related to Warrior Met Coal, including insider transactions and earnings reports.
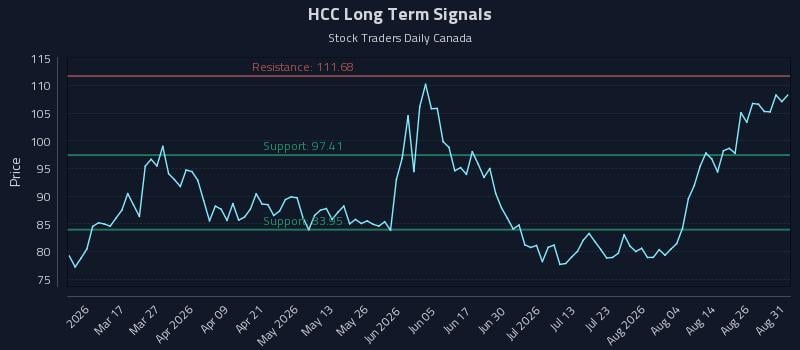
This article provides an in-depth analysis of Warrior Met Coal Inc. (NYSE: HCC), highlighting strong sentiment and an overweight bias across all trading horizons. It details institutional trading strategies, including position, momentum breakout, and risk hedging, along with multi-timeframe signal analysis to optimize position sizing and minimize drawdown risk. The analysis indicates an exceptional risk-reward short setup for HCC.
Walter J. Scheller, CEO of Warrior Met Coal, sold 50,000 shares of common stock for $5.5 million under a pre-planned Rule 10b5-1 trading plan. This transaction represents 16% of his equity holdings prior to the sale, but he retains $28.5 million in direct ownership. The sale occurred after an 80% stock appreciation over the past year, and analysts anticipate significant earnings growth for the company in the coming years.
Warrior Met Coal (HCC) has shown strong returns over five years, with its Blue Creek mine progressing ahead of schedule, suggesting potential undervaluation based on a Discounted Cash Flow (DCF) model. While the DCF model points to a significant discount, other valuation checks and its P/E ratio indicate the stock might be fairly valued. The article highlights a split in community narratives regarding the stock's future, with bulls focusing on Blue Creek's impact and bears on structural coal risks.
Walter J. Scheller, CEO and Director of Warrior Met Coal, Inc., sold 50,000 shares of company stock at $105 per share on August 19, 2026. This transaction was executed under a pre-arranged Rule 10b5-1 trading plan established on March 2, 2026. After the sale, Scheller directly holds 317,793 shares of Warrior Met Coal common stock.
Warrior Met Coal (HCC) saw its stock rise by 6.8% after reporting a significant increase in second-quarter revenue and net income, driven by stronger customer adoption of its Blue Creek volumes. The company also raised its full-year coal sales guidance, reinforcing its near-term investment narrative despite ongoing risks related to global steel demand and decarbonization pressures. Analysts project strong future revenue and earnings, with a fair value indicating a modest upside.