

OUTFRONT Media Inc. (OUT) is a leading provider of advertising space on out-of-home advertising structures and sites across the United States, Canada, and Latin America. The company's portfolio primarily consists of billboards but also includes transit displays, street furniture, digital displays located in transit systems, and mobile displays on buses, trains, and platforms.
OUTFRONT Media was established in 2014 after CBS Corporation, a significant media company, decided to split off its outdoor advertising business. Headquartered in New York, the firm has a team of professionals that offers a comprehensive suite of inventory solutions. They create customized, impactful brand experiences through a combination of traditional out-of-home (OOH) and modern digital advertising strategies.
OUTFRONT Media's business model focuses on leasing its advertising space to diverse clients across various sectors, including retail, entertainment, services, telecom, healthcare, and technology, among others. The primary revenue source for the company is its advertising contracts that are usually short-term, ranging from a few weeks to a year.
One of the unique selling points of OUTFRONT Media is its ability to connect brands with consumers beyond the traditional media channels. Instead of focusing only on mass media like television or the internet, the firm takes advantage of physical spaces in the environment that are highly trafficked but often overlooked.
Despite the rise of digital media, OUTFRONT Media believes in the power of out-of-home advertising's undeniable impact. According to several studies, consumers are more likely to remember and engage with out-of-home ads than those they encounter online, mainly when they are placed strategically in high-traffic areas.
Simultaneously, the company has embraced digital transformations in the OOH industry by introducing interactive digital billboards that can adjust their content based on weather conditions or time of day. Utilizing cutting-edge technology and actionable data, OUTFRONT's digital solutions aim to offer a more dynamic, timely, and relevant advertising experience.
With a commitment to excellence, OUTFRONT Media follows a rigorous approach in everything it does, from designing innovative marketing campaigns to ensuring safety and quality in outdoor advertising infrastructure. In a rapidly changing media landscape, the company strives to stay ahead of the curve, helping advertisers communicate their brand stories more effectively and creatively to captivate their target audiences.
Simultaneously, OUTFRONT Media stands committed to social responsibility. It uses its platform to support numerous community and social initiatives, reflecting its dedication to making a positive impact in society.
Despite the proliferation of digital and social media channels, OUTFRONT Media continues to prove that its form of advertising is an essential part of a comprehensive ad strategy. As such, it continues to thrive as a trustworthy and innovative leader in the out-of-home advertising industry.
Income statement
Balance sheet statement
Cash flow statement
Current assets / Current liabilities
Equity / Debt / Cash
Dividends
Outfront Media (OUT) has experienced a 6.5% decline in its stock price over the past four weeks, but indicators suggest a potential trend reversal. The stock's Relative Strength Index (RSI) of 28.39 indicates it is oversold, while Wall Street analysts have shown strong agreement in raising earnings estimates for the current year. Furthermore, Outfront Media currently holds a Zacks Rank #2 (Buy), pointing to a likely turnaround in the near term.
Outfront Media (OUT) has seen a 6.2% decline over the past four weeks, placing it in oversold territory according to the Relative Strength Index (RSI) with a reading of 29.67. This technical indicator, combined with a 1% increase in consensus EPS estimates from analysts and a Zacks Rank #2 (Buy), suggests that the stock may be poised for a trend reversal and potential price appreciation.
This article explains Digital Out-of-Home (DOOH) advertising, highlighting its distinction from web ads due to its one-to-many reach on public screens. It details the mechanics, evolution, and growth of programmatic DOOH, including key industry players, protocol standardization, and the unique challenges of measurement and verification compared to other digital channels. The piece also covers recent market consolidations, advancements in AI-powered campaigns, and ongoing debates regarding verification and inventory limitations.
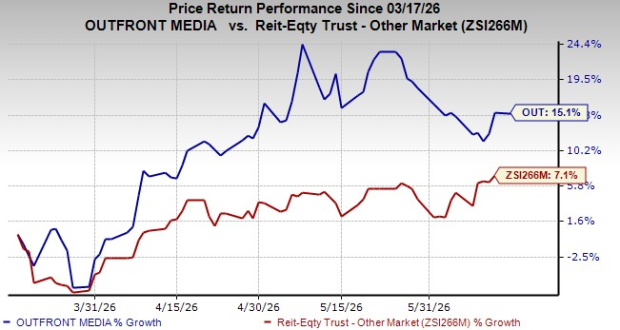
OUTFRONT Media (OUT) is demonstrating key trends in out-of-home (OOH) advertising, driven by its digital conversion, automated sales, and premium transit inventory. While these advancements and ad-tech partnerships signal a flexible model, the company still navigates regulatory hurdles, municipal contracts, and inflation-linked costs. OUT's performance offers insights into the evolving OOH landscape, balancing growth opportunities with real-world operational challenges.

Outfront Media (OUT) shares recently jumped 5% after the last trading session, driven by increased investor optimism and impressive trading volume. The company is projected to report strong quarterly funds from operations (FFO) and revenue growth, with FFO estimates already revised upward. This positive trend in FFO estimate revisions often signals future stock price appreciation, making OUT a stock to watch.
The article highlights Outfront Media (OUT) as a strong value stock, based on Zacks' proprietary Style Scores and Rank system. OUT is noted for its favorable valuation metrics, including a forward P/E ratio of 14.19, contributing to its "B" Value Style Score and "B" VGM Score. Investors are encouraged to consider stocks with high Zacks Ranks and strong Style Scores for potential market outperformance.
OUTFRONT Media (OUT) is gaining investor attention due to improvements in digital and transit advertising in 2026. The company benefits from a wide national footprint, increasing transit demand, and digital conversions, which are balanced against advertising cyclicality and capital needs. Despite these positive trends, the outlook remains balanced, with a Zacks Rank #3 (Hold) due to ongoing competition and capital intensity.