

YETI Holdings, Inc. (YETI), is a fast-growing company that designs, markets and distributes premium products for the outdoor and recreational industry. YETI is perhaps best known for its wide range of heavy-duty coolers, but they also produce a variety of outdoor living products, such as drinkware, outdoor gear, bags, and more. The Austin, Texas-based company has quickly made a major dent in the outdoor living industry, with an increasing consumer demand for its high-quality, durable products and iconic YETI branding.
Established in 2006 by Roy and Ryan Seiders, YETI quickly positioned itself as a premium brand catering to outdoor enthusiasts. The Seiders brothers’ original aim was to create a cooler that wouldn’t break - something that could withstand the rigorous demands of a serious outdoor lifestyle.
The result was YETI's first hard cooler, capable of keeping its contents cold for days on end and resilient enough to resist the maulings of a grizzly bear. While these heavy-duty coolers came at a premium price, they were quickly embraced by hunters, fishermen, and campers. The quality of the products validated the price tag, a key factor in the company's success.
Beyond coolers, YETI has expanded its product roster to include drinkware like tumblers and mugs, bags, and other outdoor accessories. They also have a portfolio of soft coolers, well-regarded for their ice retention capabilities and durability. The brand's products now span beyond the initial outdoor niche to areas like everyday living, work, travel, and various types of outdoor activities.
Strategically, YETI has adopted a multi-pronged approach to reach its audience. Its sales occur through a wide range of channels such as wholesale, which includes specialty outdoor retailers and larger chain stores, direct-to-consumer channels such as its company-owned website and retail stores, and through international operations throughout Canada, Australia, and other locations around the world.
The core of YETI's success lies in its commitment to quality and innovation. It's all about creating products that not only serve the intended purpose, but exceed all expectations in terms of performance and durability. The company has based its reputation on this commitment and has built a loyal customer base that appreciates the value they are getting for their money.
The business's innovative and quality-centric approach places YETI Holdings, Inc. (YETI) in a strong position for further growth. As the outdoor and recreational market continues to expand, there's no doubt that YETI will remain at the forefront, continuously revolutionizing the world of outdoor gear and products with their exceptional product offerings.
Income statement
Balance sheet statement
Cash flow statement
Current assets / Current liabilities
Equity / Debt / Cash
Dividends
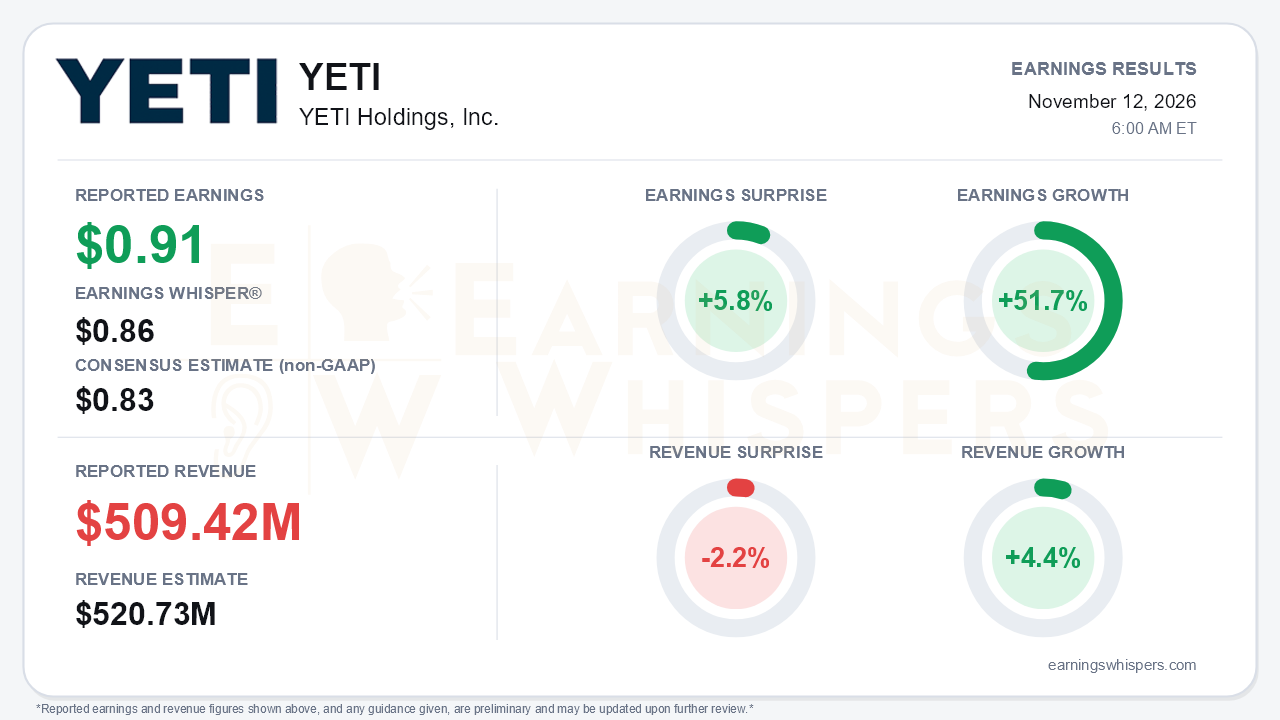
YETI Holdings reported a Q3 profit beat but a revenue miss, coupled with its first guidance cut of the year, signaling a shift in its financial trajectory. While adjusted EPS exceeded expectations due to margin improvements driven by lower tariffs and operational efficiencies, U.S. demand softened, impacting DTC and cooler sales. The company's outlook for full-year sales and EPS has been lowered, highlighting concerns about top-line growth despite increased profitability.

Yeti Holdings has lowered its full-year sales outlook, anticipating continued consumer caution through the holiday quarter. This adjustment comes after the cooler and drinkware maker's third-quarter sales, while up year-over-year, fell short of Wall Street's projections. CEO Matt Reintjes noted uneven demand, particularly in the U.S. and Canada.

YETI Holdings (YETI) is showing an improving earnings outlook with analysts forecasting higher profit per share and stronger performance. The stock has seen a recent near-term climb, with a 1-month return of 15.18%, and Simply Wall St's analyst consensus Narrative suggests it is 16.6% undervalued, with a fair value of $54.93 compared to its latest close of $45.83. However, based on simple earnings multiples, the stock trades at a P/E of 18.7x, which is slightly above its peer average.

YETI (NYSE:YETI) is scheduled to release its Q3 2026 earnings before market open on Thursday, November 12th, with analysts expecting $0.84 EPS on $523.21 million in revenue. The company previously beat estimates in Q2 2026, reporting $0.67 EPS against a $0.54 consensus. Analysts currently rate YETI stock a "Moderate Buy" with an average price target of $55.20.
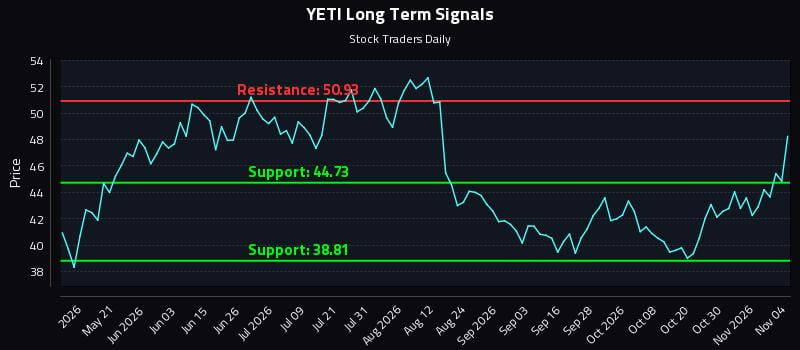
This article analyzes Yeti Holdings Inc. (NASDAQ: YETI), highlighting a mid-channel oscillation pattern and a strong risk-reward short setup. AI models have generated three distinct trading strategies—Position Trading, Momentum Breakout, and Risk Hedging—each with specific entry zones, targets, and stop losses. The analysis also provides multi-timeframe signal strengths and support/resistance levels for the stock.

Debate surrounds YETI Holdings (YETI) valuation, with some seeing it as undervalued due to productivity savings and a clear path for revenue growth, while others point to inflation and premium P/E levels. Despite a recent rebound, the stock remains below intrinsic fair value estimates and analyst targets, prompting investors to weigh whether the current premium is justified by earnings quality. The company's P/E ratio of 18.5x is above the fair ratio estimate and global leisure average, signaling both optimism and potential compression risk.
YETI Holdings' stock is trading around US$45, which is being evaluated against its earnings profile after a 56.7% fall over five years. The current P/E ratio of 18.5x places it above the Leisure industry average but below its peer group, suggesting it might be overvalued when considering its growth, profitability, size, and risk. Analysts present both bull and bear cases, with the former seeing the stock as 17% undervalued due to productivity savings and raised margin guidance, while the latter views it as 6% overvalued due to inflation and cost headwinds.